
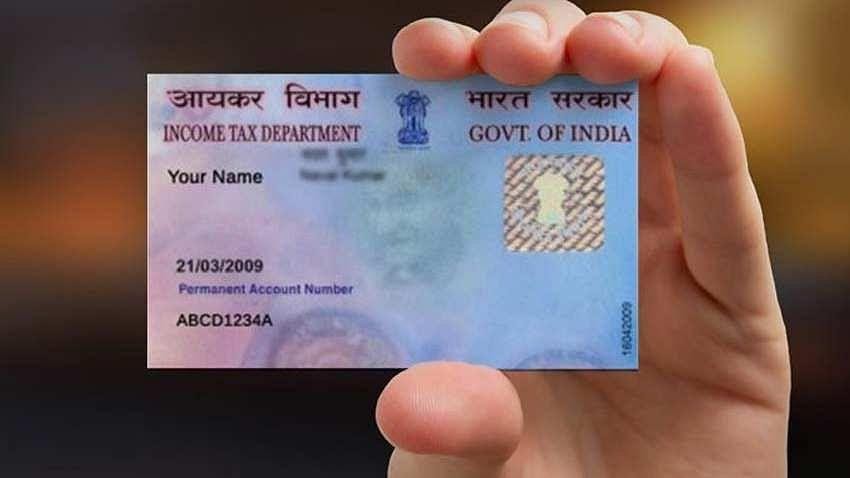
The permanent account number should be quoted as follows:
1. QUOTE OWN PERMANENT ACCOUNT NUMBER IN RETURNS, CERTIFICATES, CORRESPONDENCE-
Every person shall quote his permanent account number (PAN) in all his returns/challans/correspondence with any income-tax authority. Besides, every person shall quote his PAN in all documents pertaining to the transactions specified in rule 114B and given in the table (infra):
| Transactions specified in rule 114B | Value of Transaction | |
| 1. | Sale or purchase of a motor vehicle (other than two wheeler) | All such transactions |
| 2. | Opening an account [other than a time-deposit referred to at Sl. No. 12 and a Basic Savings Bank Deposit Account] with a bank/co-operative bank | All such transactions |
| 3. | Making an application to a bank/co-operative bank/any other company or institution, for issue of a credit or debit card | All such transactions |
| 4. | Opening of a demat account | All such transactions |
| 5. | Payment to a hotel or restaurant against a bill or bills at any one time | Payment in cash of an amount exceeding Rs. 50,000 |
| 6. | Payment in connection with travel to any foreign country or payment for purchase of any foreign currency at any one time. | Payment in cash of an amount exceeding Rs. 50,000 |
| 7. | Payment to a Mutual Fund for purchase of its units | Amount exceeding Rs. 50,000 |
| 8. | Payment to a company or an institution for acquiring debentures/bonds issued by it | Amount exceeding Rs. 50,000 |
| 9. | Payment to the RBI for acquiring bonds issued by it | Amount exceeding Rs. 50,000 |
| 10. | Deposit with a bank/co-operative bank | Deposits in cash exceeding Rs. 50,000 during any one day or exceeding Rs. 2,50,000 during November 9, 2016 and December 30, 2016 |
| 11. | Purchase of bank drafts/pay orders/banker’s cheques from a bank/co-operative bank | Payment in case for an amount exceeding Rs. 50,000 during any one day |
| 12. | A time deposit with bank/co-operative bank/post office/Nidhi/non-banking financial company | Amount exceeding Rs. 50,000 or aggregating to more than Rs. 5,00,000 during a financial year |
| 13. | Payment for one or more pre-paid payment instruments to a bank/co-operative bank/any other company or institution | Payment in cash or by way of a bank draft/pay order/banker’s cheque of an amount aggregating to more than Rs. 50,000 in a financial year |
| 14. | Payment as life insurance premium to an insurer | Amount aggregating to more than Rs. 50,000 in a financial year |
| 15. | A contract for sale or purchase of securities (other than shares) | Amount exceeding Rs. 1,00,000 per transaction |
| 16. | Sale or purchase, by any person, of shares in a company not listed in a recognised stock exchange | Amount exceeding Rs. 1,00,000 per transaction |
| 17. | Sale or purchase of any immovable property | Amount exceeding Rs. 10,00,000 or valued by stamp valuation authority referred to in section 50C at an amount exceeding Rs. 10,00,000 |
| 18. | Sale or purchase, by any person, of goods or services of any nature other than those specified at Sl. Nos. 1 to 17 above | Amount exceeding Rs. 2,00,000 per transaction |
The following points should be noted:
A) Where a person, entering into any transaction referred to in the Table (supra), is a minor and who does not have any income chargeable to income-tax, he shall quote PAN of his father or mother or guardian, as the case may be, in the relevant document.
B) Any person who does not have PAN and who enters into any transactions given above, he shall make a declaration in Form No. 60 giving therein the particulars of such transaction. The declaration in Form No. 60 can be made either in paper form or electronically under the electronic verification code.
C) The above provisions of quoting PAN is not applicable in case of following persons-
a)Central Government, the State Governments and the Consular Offices;
b)Non-resident in respect of transactions other than a transaction referred to at Sl. Nos. 1,2,4,7,8,10,12,14,15,16,17 of the Table (supra).
D) “Payment in connection with travel” includes payment towards fare, or to a travel agent or a tour operator, or to an authorised person.
E) “Travel agent or tour operator” includes a person who makes arrangements for air, surface or maritime travel or provides services relating to accommodation, tours, entertainment, passport, visa, foreign exchange, travel related insurance or other travel related services either severally or in package.
F) “Time deposit” means any deposit which is repayable on the expiry of a fixed period.
2. QUOTE PERMANENT ACCOUNT NUMBER OF RECIPIENT/ PURCHASER IN TAX DEDUCTION/COLLECTION AT SOURCE –
The following provisions have been made with effect from June 1, 2001:
A) Tax Deduction At Source [Sec. 139A (5B)] –
Where any sum or income has been paid after deducting tax, every person deducting tax shall quote the permanent account number of the recipient, in a statement furnished in accordance with the provisions of section 192(2C), in all certificates furnished in accordance with the provision of section 203 (Form Nos. 16, 16A) and in all returns annual/quarterly (I.e. Form Nos. 24, 26, 24Q, 26Q and 27Q, etc.)
B) Tax Collection At Source [Sec. 139A (5C)]-
Every seller collecting tax under section 206C shall quote the permanent account number of every buyer, in all certificates furnished in accordance with the provisions of section 206C(5) and in all returns to an income-tax authority.